
📢 Disclosure: This post contains affiliate links. We may earn a commission at no extra cost to you. We only recommend products we genuinely believe in.
Learning how to retire early usually means building enough financial flexibility that paid work becomes optional before traditional retirement age. The FIRE framework — Financial Independence, Retire Early — can help organize that goal, but there is no single formula that guarantees success. Your savings rate, spending, taxes, healthcare costs, investment returns, withdrawal strategy, and retirement length all matter. This guide explains the main calculations and tradeoffs to consider in 2026.
What Does It Mean to Retire Early?
Retiring early generally means reaching a level of financial independence where your investments, savings, and other income sources can support your planned spending without relying on full-time employment. That does not necessarily mean never working again. Some people continue part-time work, consulting, or other paid activity because they enjoy it or because it reduces pressure on the portfolio.
The typical FIRE goal is to retire early — often in your 40s or even 30s — rather than at the traditional retirement age of 65. The earlier you reach financial independence, the more years of freedom you gain. Someone who achieves financial independence at 45 instead of 65 gains 20 additional years of life outside mandatory employment — two full decades of time, health, and freedom that traditional retirement planning simply does not deliver.
What Is Your FIRE Number?
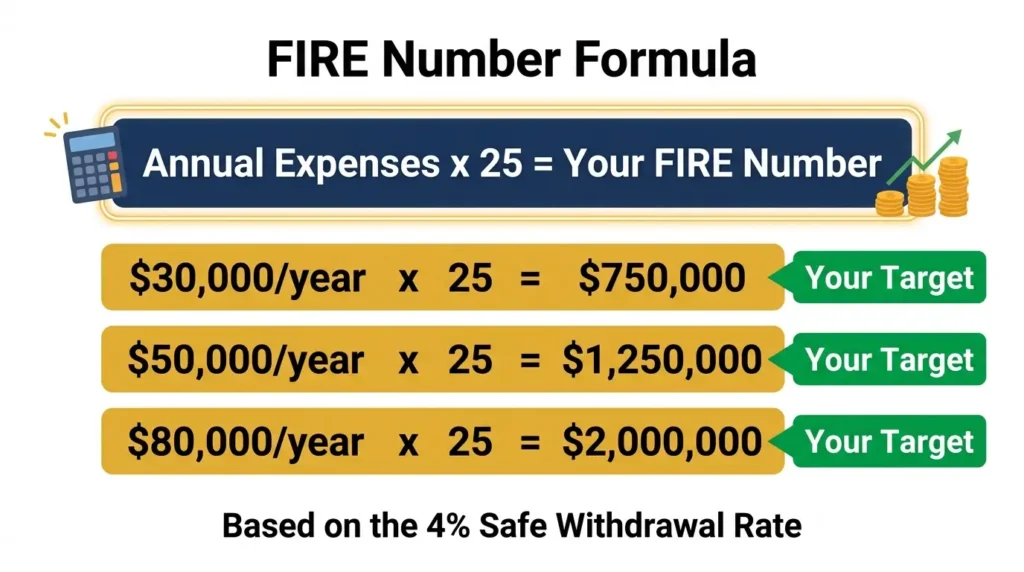
A common starting point is to estimate a FIRE number — the portfolio size that may support your planned spending. Many FIRE calculators use the 4% rule as a rough benchmark, which implies multiplying annual spending by 25. But this is a planning heuristic, not an exact target or guarantee, and it was developed from historical retirement research focused largely on roughly 30-year periods.
A simple 4% starting assumption is: annual expenses × 25. For a longer early-retirement horizon, many people also test lower initial withdrawal assumptions and multiple market scenarios.
| Annual Expenses | FIRE Number (25x) | Monthly Withdrawal at 4% | Lifestyle Description |
|---|---|---|---|
| $25,000/year | $625,000 | $2,083/month | Lean FIRE — frugal, minimal |
| $40,000/year | $1,000,000 | $3,333/month | Standard FIRE — comfortable |
| $60,000/year | $1,500,000 | $5,000/month | Standard FIRE — comfortable |
| $100,000/year | $2,500,000 | $8,333/month | Fat FIRE — luxurious lifestyle |
Your FIRE estimate changes when your spending assumptions change. Lower ongoing expenses can reduce the portfolio required under a given withdrawal-rate assumption and may also increase the amount you can save. But healthcare, taxes, housing, dependents, and future lifestyle changes can push spending higher as well. Read our guide on what net worth is to track your progress alongside your retirement target.
How Savings Rate Affects Your FIRE Timeline
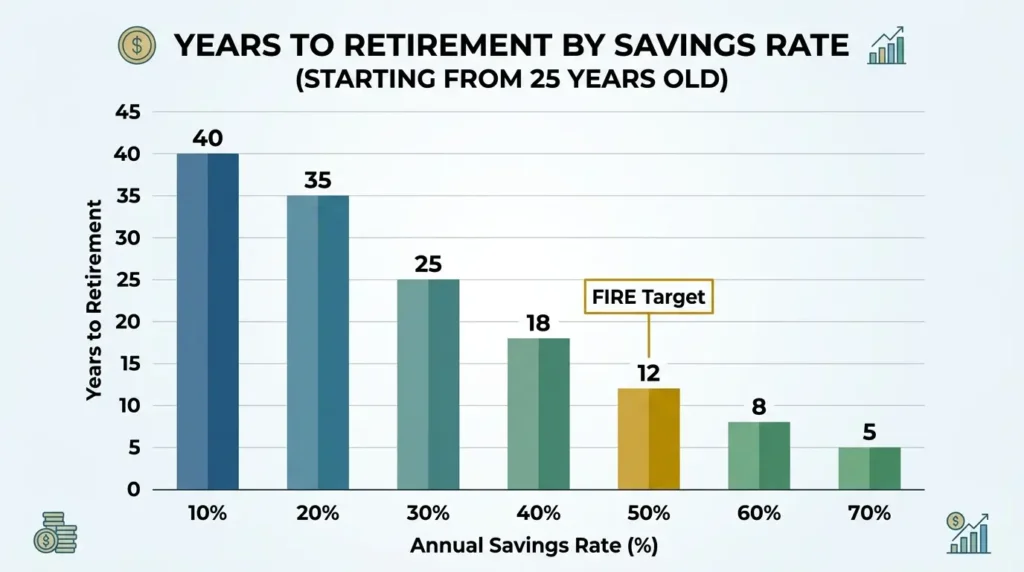
Your savings rate is one of the biggest variables in an early-retirement plan because it affects both how quickly you accumulate assets and how much of your income you are learning to live without. The table below is only an illustration based on simplified assumptions, including a 7% real return and starting from zero; actual results can differ substantially.
| Savings Rate | Years to Financial Independence | Retire Early at (Starting at 25) |
|---|---|---|
| 10% | ~40 years | Age 65 (traditional retirement) |
| 20% | ~35 years | Age 60 |
| 30% | ~25 years | Age 50 |
| 40% | ~18 years | Age 43 |
| 50% | ~12 years | Age 37 |
| 60% | ~8 years | Age 33 |
| 70% | ~5 years | Age 30 |
A higher savings rate can shorten a projected path to financial independence under the same return and spending assumptions, but the exact timeline depends on market returns, taxes, account types, inflation, and future spending. Increasing income and controlling expenses can both improve the gap available to save and invest. Read our guide on how to build wealth in your 30s for a broader framework.
Types of FIRE: Which Path Is Right for You?
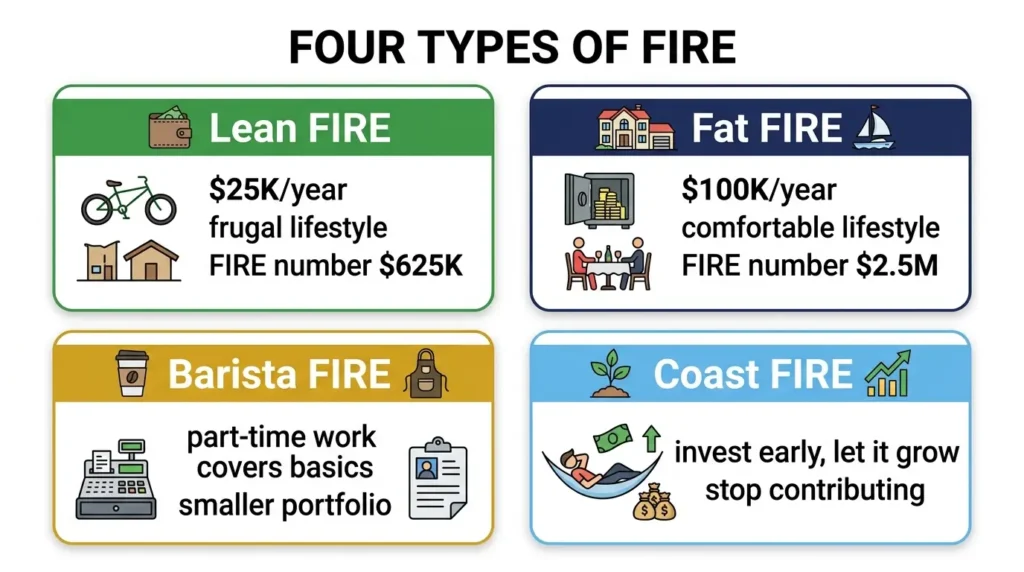
Lean FIRE
Lean FIRE means retiring early on a frugal budget — typically $25,000–$40,000/year in expenses, requiring a portfolio of $625,000–$1,000,000. Lean FIRE is achievable faster because both the required portfolio is smaller and the savings rate tends to be higher due to reduced spending. Best for people who genuinely value minimalism and low-consumption lifestyles over material abundance.
Fat FIRE
Fat FIRE means retiring early with a comfortable or even luxurious lifestyle — typically $80,000–$150,000/year in expenses, requiring a portfolio of $2,000,000–$3,750,000. Fat FIRE takes longer to achieve but provides financial independence without lifestyle sacrifice. Best for high earners who want freedom without giving up travel, dining, and experiences.
Barista FIRE
Barista FIRE is a hybrid approach: you build a smaller portfolio that covers most expenses, then supplement with part-time or flexible work that covers the rest. The “barista” name comes from working a low-stress part-time job (like a barista) for income and health benefits while your portfolio continues growing. Best for people who want to escape full-time employment before their full FIRE number is reached.
Coast FIRE
Coast FIRE means investing aggressively early in your career until your portfolio is large enough to grow to your FIRE number on its own — without any additional contributions. Once you hit your Coast FIRE number, you can “coast” — work a lower-stress, lower-paying job just to cover living expenses, while your existing portfolio compounds to full FIRE by traditional retirement age. This is the most accessible form of retire early planning for people in their 20s and early 30s.
How to Invest to Retire Early
An early-retirement investing plan usually needs to balance diversification, fees, taxes, liquidity, and access rules. Tax-advantaged accounts can be valuable, but taxable assets may also matter because early retirees can need funds before traditional retirement-account access ages.
- Review your employer retirement plan and any matching formula. If a match is available, understand the contribution level needed to receive it, along with vesting and eligibility rules. The employee elective-deferral limit for 401(k) plans is $24,500 in 2026.
- Consider an IRA if eligible. The 2026 IRA contribution limit is $7,500, or $8,600 if age 50 or older, subject to compensation and Roth IRA income rules. Qualified Roth IRA withdrawals can be tax-free. Read our guide on what a Roth IRA is.
- Decide whether additional 401(k) contributions fit your tax strategy, employer plan options, and need for accessible funds before traditional retirement age.
- Consider a taxable brokerage account for flexible access, while accounting for capital-gains and dividend taxes.
- Compare diversified low-cost funds based on the index tracked, fees, account compatibility, tax considerations and your risk tolerance. Read our guide on how to invest in index funds and our 2026 index fund comparison.
Early retirees also need an access strategy. Retirement accounts can have age-based distribution rules and exceptions, while taxable brokerage assets are generally more flexible. Do not assume you must fund the entire bridge period from one account type; tax planning can involve several account types and withdrawal methods.
The 4% Safe Withdrawal Rate Explained
The 4% rule is a widely used retirement-planning benchmark, not a guaranteed safe withdrawal rate. The classic approach starts with a withdrawal equal to 4% of the initial portfolio and then adjusts that dollar amount for inflation. Historical research often evaluated roughly 30-year retirement periods, while very early retirement can involve a much longer horizon and greater sequence-of-returns risk.
- You have a $1,500,000 portfolio
- Year 1: You withdraw $60,000 (4% of $1.5M)
- Year 2: You withdraw $61,800 (adjusted 3% for inflation)
- The remaining portfolio stays invested, but future returns can be positive or negative and are not guaranteed to sustain the planned withdrawals
For a 40-, 50-, or even longer retirement horizon, it is useful to test multiple starting withdrawal rates rather than assuming 4% will work automatically. A lower starting rate such as 3%–3.5% implies a larger starting portfolio, while flexible spending, part-time income, taxes, asset allocation and market conditions can also materially affect outcomes.
Practical Steps to Retire Early Starting Today
- Calculate your current annual expenses — track every dollar spent for 3 months to get an accurate number
- Estimate a FIRE range — test annual expenses against several withdrawal-rate assumptions instead of relying only on the 25× shortcut
- Calculate your current net worth — the gap between your FIRE number and your net worth is the work ahead. Read our guide on what is net worth.
- Improve your savings rate where practical — review large recurring expenses, income opportunities and how much you can invest without weakening your emergency reserves
- Compare available tax-advantaged accounts — including a 401(k), IRA and HSA when eligible — alongside the need for accessible taxable assets
- Choose an asset allocation that fits your risk tolerance, time horizon and withdrawal plan; broad low-cost index funds can be useful building blocks, but a 100% stock allocation is not appropriate for every early retiree
- Track progress periodically — update spending, savings, portfolio value and assumptions rather than focusing only on short-term market movements
- Build a withdrawal and tax plan — consider account access rules, taxes, healthcare costs, cash reserves and how spending could adjust during weak markets
The full financial plan framework for reaching these milestones is in our guide on how to create a financial plan. And for the decade-specific strategy for your 20s, read our guide on saving for retirement at 25 — the earlier you start, the lower your required savings rate to retire early.
Frequently Asked Questions
How much money do I need to retire early?
A common FIRE starting point is 25 times annual expenses, which corresponds to a 4% initial withdrawal assumption. For example, $50,000 of annual spending implies $1,250,000 and $40,000 implies $1,000,000. This is a planning estimate, not a guarantee; very early retirement may require testing lower withdrawal rates and longer time horizons. Reducing your annual expenses is the fastest way to lower your required number.
How to retire early with a normal income?
Most FIRE success stories come from people with average incomes who achieved a high savings rate — not high earners. On a $70,000 household income, saving and investing 40%–50% ($28,000–$35,000/year) can reach financial independence in 15–20 years. The key levers are: minimize housing costs (keep below 25% of income), eliminate car debt, cook at home, and invest 100% of income increases rather than inflating your lifestyle.
What age can you realistically retire early?
A higher savings rate can shorten a projected path to financial independence under a given set of assumptions, but there is no guaranteed retirement age. Market returns, inflation, taxes, healthcare costs, starting assets and future spending all affect the outcome. Many FIRE practitioners retire in their 40s on incomes of $80,000–$120,000 per household — not by earning more, but by spending significantly less than their peers.
What do you do for health insurance when you retire early?
Health coverage is one of the most important planning issues for people retiring before Medicare eligibility at 65. Options may include ACA Marketplace coverage, coverage through a spouse’s employer, qualifying part-time employment benefits, or COBRA for a limited transition period. Premiums, deductibles, subsidies, networks and out-of-pocket limits should all be included in the retirement budget. Many FIRE practitioners build healthcare costs directly into their annual expense estimate when calculating their FIRE number.
Is the 4% rule safe for early retirement?
The classic 4% rule is commonly associated with roughly 30-year retirement horizons and historical market testing. Early retirees may face a much longer drawdown period, so it is prudent to test lower starting withdrawal rates, flexible spending, and multiple market scenarios rather than treating 4% as automatically safe. Most FIRE practitioners also maintain flexibility — reducing withdrawals during market downturns, doing occasional consulting work, or building in a cash buffer — to make the 4% rule more robust over longer periods.
Final Thoughts: How to Retire Early Is a Choice Available to More People Than They Think
Knowing how to retire early is not about escaping work — it is about building a life where work is optional. The FIRE framework gives you a clear mathematical target, a proven investment strategy, and the freedom to design your own timeline. Whether you aim for Lean FIRE at 35, Standard FIRE at 45, or Fat FIRE at 55, the path is the same: maximize your savings rate, minimize expenses, invest consistently in low-cost index funds, and let compound interest close the gap between where you are and where you want to be.
Every dollar you save and invest today is a dollar that earns more dollars while you sleep. That compounding, sustained over 10–20 years with discipline and intention, is how to retire early. Start tracking your FIRE number today, maximize every tax-advantaged account available to you, and commit to a savings rate that makes your early retirement timeline real.